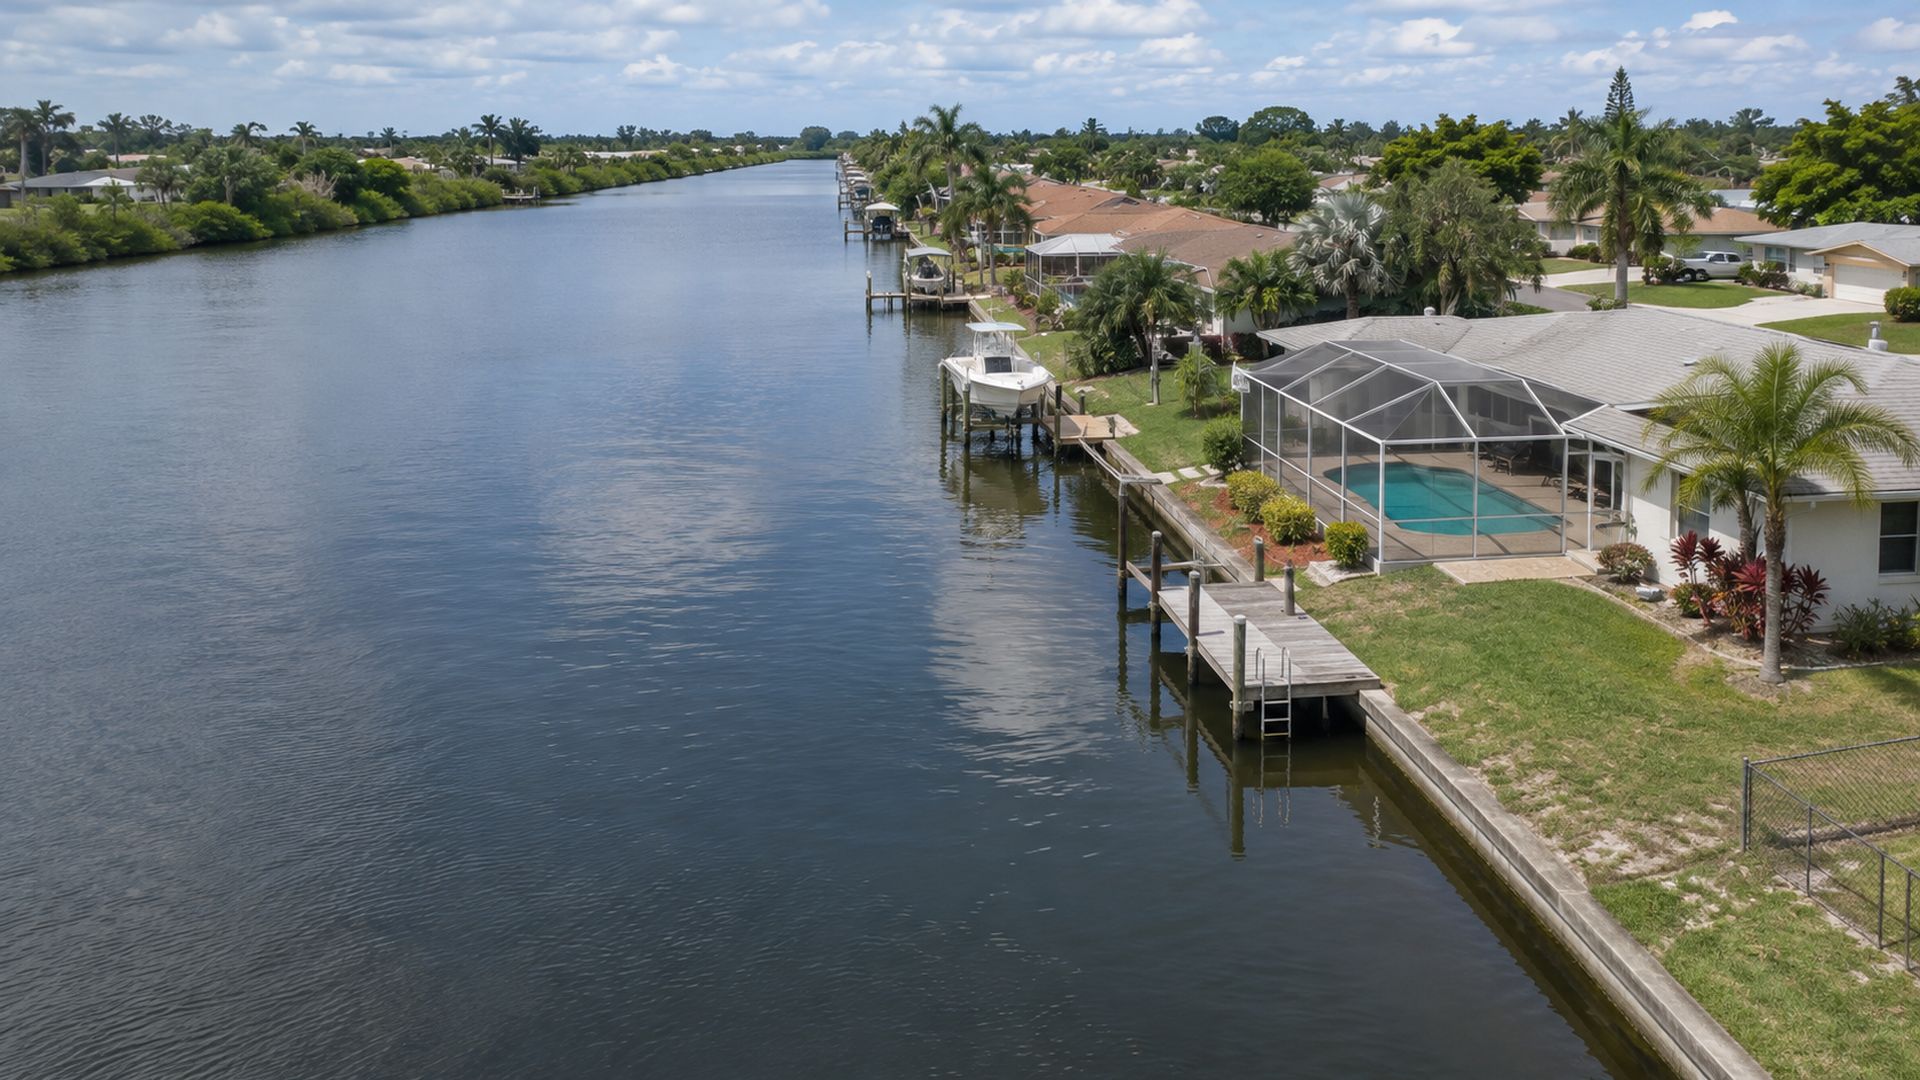
Cape Coral has more miles of canals than any city in the world, and its waterfront homes, Gulf-access lots and pool homes have drawn retirees and families from all over the country. Lee County values cooled after 2022, but owners from before 2020 are still well ahead. On Mortgage lends statewide, fully online, so a Cape Coral homeowner can tap that equity without refinancing a low first mortgage.
These are the current HELOC rates we’re posting for Cape Coral homeowners. Today’s home equity line of credit rates start at 6.75% APR* and are personalized to your equity, credit and property. Checking your rate won’t affect your credit score.
Here is the local picture behind the equity in a Cape Coral home.
Zillow’s typical value is about $335,000. Gulf-access canal homes in the Southwest and Yacht Club areas run much higher.
Lee County values are up about 37% since early 2020. Lee is about 19% off its 2022 peak, one of the steepest pullbacks in Florida, so long-time owners have the equity and newer buyers may not.
Gulf-access and freshwater canals make docks, lifts and seawalls part of owning a home here.
Approximate figures from U.S. Census (ACS) and Zillow (2026). Home values move. Your line is based on a current appraisal of your Cape Coral home.
If you bought your Cape Coral home before the last few years of price growth, or you have simply been paying down your mortgage, you may be holding hundreds of thousands of dollars in equity that a HELOC can put to work, without touching the low rate on your first mortgage.
Here is the shape of it in plain numbers. Say your Cape Coral home is worth $400,000 and you owe $170,000. A HELOC that lets you reach up to 90% of value could open a line as large as roughly $190,000, the difference between 90% of the home’s value ($360,000) and your existing balance. You only pay interest on what you actually draw, so the full line can sit ready without costing you a dime until you use it.
Most Cape Coral owners who bought or refinanced a few years ago are sitting on a first mortgage in the 3% to 4% range. A cash-out refinance would replace that low rate with today’s higher one across your entire balance. A HELOC leaves your first mortgage exactly where it is and adds a separate line only on the equity you want to tap.
We work with homeowners and investors throughout Lee County.
Gulf-access canal homes, Cape Harbour and the established streets around the Cape Coral Yacht Club.
The older, more central neighborhoods near Cape Coral Parkway and the bridges to Fort Myers.
Newer construction on larger lots, freshwater canals and the areas still filling in as the city grows.
Own a home anywhere in Lee County, or elsewhere in Florida? Start your application and we’ll show you what your equity can do.
Here is how we handle the situations that actually come up here.
Seawall replacement and lift installs are common here. A HELOC funds them as the marine contractor bills.
Owners in the expansion areas face water and sewer assessments. A HELOC pays the assessment off and leaves the first mortgage alone.
Roofs, lanais and pool cages damaged in recent storms. A HELOC funds repairs the insurer did not fully cover.
Many Cape homes belong to snowbirds. Second homes and rentals are eligible.
A new pool, cage or lanai on a Cape lot is a classic HELOC project, drawn in stages.
Contractors, realtors and small business owners make up much of the city. The Bank Statement HELOC qualifies on deposits.
Cape Coral was built by contractors, realtors and small business owners, and many still work for themselves. If your tax return shows far less than your deposits, the Bank Statement HELOC qualifies you on 12 months of bank statements with an expense factor as low as 25% and a 660 minimum credit score. Strong credit and plenty of equity? The No-Doc HELOC skips income documentation altogether.
If you locked a first mortgage in the 3s or low 4s, protecting it matters. A HELOC sits alongside your existing loan instead of replacing it, so you tap equity without resetting your whole mortgage at today’s rates.
Every situation is different, but the reasons Cape Coral owners tap their equity tend to rhyme:
No generic teaser numbers. Tell us about your Cape Coral home and finances, and we’ll show you a rate built around your equity, not somebody else’s.
Whether you are salaried, self-employed, investing or would rather not document income at all, there is a program built for your situation.
The core line of credit for Cape Coral homeowners: $50,000 to $1,000,000, up to 90% of value, fully online.
Qualify on 12 months of bank statements instead of tax returns. 660 minimum credit.
For Cape Coral business owners, 1099 contractors and freelancers whose write-offs shrink their income on paper.
No income verification at all: no tax returns, W-2s or pay stubs. 700+ credit, up to 60% of value.
A line of credit on a Cape Coral rental, second home or investment property, without touching the first mortgage.
A fixed-rate lump sum up to $750,000. Qualify with bank statements, a CPA P&L or 1099s.
We lend across all of Florida. If you own property nearby, these local guides may help too.
Cape Coral HELOC rates starting at 6.75%*, personalized to you in minutes.