Serving homeowners across the entire state of Florida Questions? Call 954-494-7288
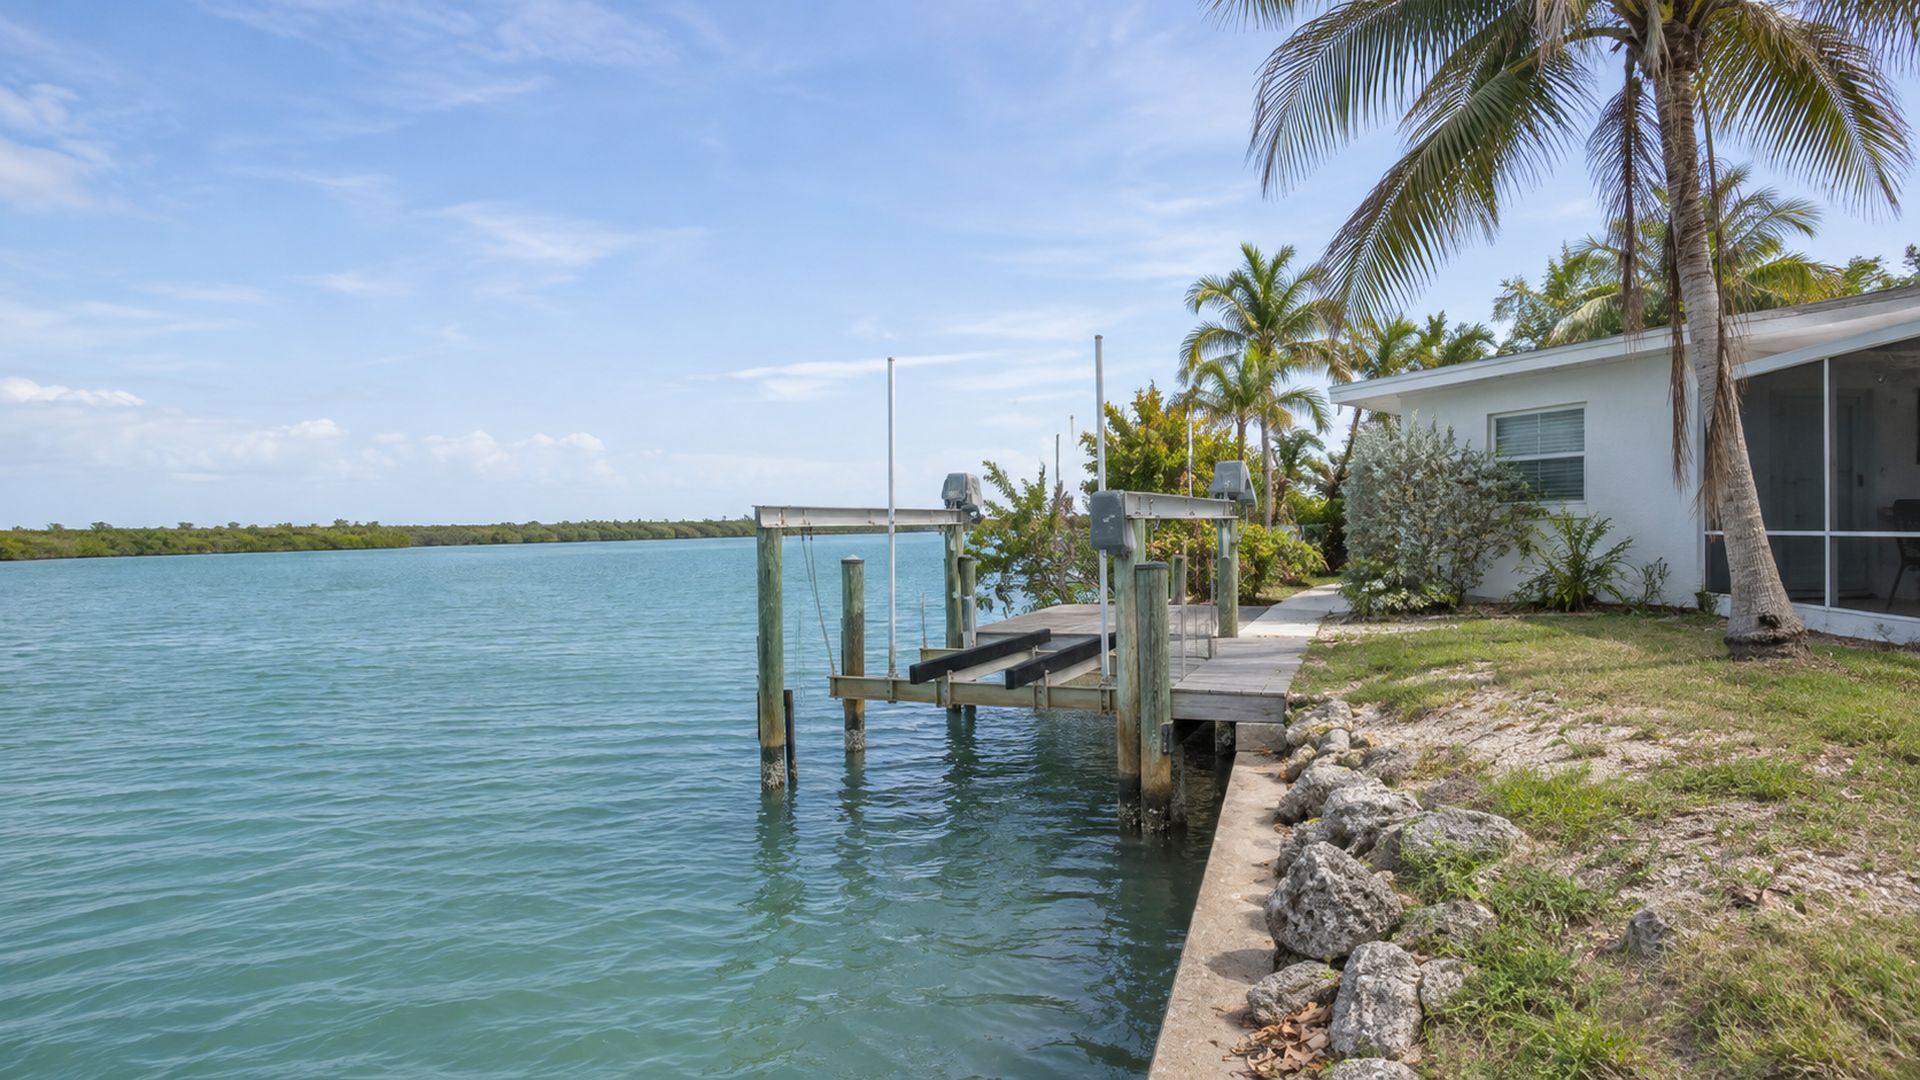
Canal-front home with a boat lift on the water, Marco Island, Florida
HELOC Home › Service Areas › Marco Island
Digital HELOC · Marco Island, Florida

Marco Island HELOC rates & home equity lines of credit

Marco Island is the largest of the Ten Thousand Islands, a Collier County community of canal-front homes with Gulf access and high-rise condos along the beach. Most owners are seasonal or retired, and many hold significant equity from years of ownership. On Mortgage lends statewide, fully online, with lines up to $1,000,000, so a Marco owner can tap equity without selling or refinancing.

6.75% Current Marco Island HELOC rate · November 2026
APR, personalized to your numbers*
Starting at 6.75%
Current HELOC rate · APR*
$50k–$1M
Line of credit
Up to 90%
Of your Marco Island home’s value
No tax returns
Bank Statement option
Current HELOC rates · updated November 2026

Marco Island HELOC rates today

These are the current HELOC rates we’re posting for Marco Island homeowners. Today’s home equity line of credit rates start at 6.75% APR* and are personalized to your equity, credit and property. Checking your rate won’t affect your credit score.

Current Marco Island HELOC rate
Starting at 6.75%
APR* · personalized to your home & credit · updated November 2026
Marco Island by the numbers

Why Marco Island homeowners are sitting on real equity

Here is the local picture behind the equity in a Marco Island home.

~$860,000

Typical Marco Island home

Zillow’s typical Marco value is about $860,000. Direct-Gulf-access estates and beachfront condos run well into seven figures.

~52%

Value growth since 2020

Collier County values are up about 52% since early 2020. Collier is about 12% off its 2024 peak, and long-time Marco owners still hold most of the gain.

Second-home island

Seasonal owners

Most Marco homes are second homes. The Digital HELOC is available on second homes and investment properties in Florida.

Approximate figures from U.S. Census (ACS) and Zillow (2026). Home values move. Your line is based on a current appraisal of your Marco Island home.

How much can Marco Island homeowners borrow right now?

If you bought your Marco Island home before the last few years of price growth, or you have simply been paying down your mortgage, you may be holding hundreds of thousands of dollars in equity that a HELOC can put to work, without touching the low rate on your first mortgage.

Here is the shape of it in plain numbers. Say your Marco Island home is worth $950,000 and you owe $300,000. A HELOC that lets you reach up to 90% of value could open a line as large as roughly $555,000, the difference between 90% of the home’s value ($855,000) and your existing balance. You only pay interest on what you actually draw, so the full line can sit ready without costing you a dime until you use it.

Why a HELOC instead of a cash-out refinance in Marco Island

Most Marco Island owners who bought or refinanced a few years ago are sitting on a first mortgage in the 3% to 4% range. A cash-out refinance would replace that low rate with today’s higher one across your entire balance. A HELOC leaves your first mortgage exactly where it is and adds a separate line only on the equity you want to tap.

Where we lend

HELOCs across every Marco Island neighborhood

We work with homeowners and investors throughout Collier County.

The Estates & canal-front homes

The canal grid with direct Gulf access, from the Tigertail area to the Estates section.

South Beach & Collier Boulevard condos

The high-rise and mid-rise condos along the beach, from the Marriott end to Cape Marco.

Old Marco, Hideaway Beach & Goodland

The island’s historic village, the gated Hideaway Beach enclave and the fishing village of Goodland.

Own a home anywhere in Collier County, or elsewhere in Florida? Start your application and we’ll show you what your equity can do.

Built for the Marco Island market

The Marco Island details other lenders trip over

Here is how we handle the situations that actually come up here.

Seawalls, docks and boat lifts

Canal-front living means marine work. A HELOC funds a seawall or lift as the contractor invoices.

Condo assessments

Florida’s milestone and reserve rules are hitting older beach towers. A HELOC pays the assessment and draws only what it costs.

Post-Ian rebuilds and elevation

Many owners are still finishing storm repairs, raising mechanicals or hardening the home. A HELOC funds the work in stages.

Seasonal and second homes

If Marco is your winter home, you can open a HELOC on it. Second homes and rentals are eligible.

Jumbo-sized lines

Lines up to $1,000,000 fit Marco values, where a large line is a modest share of the equity.

Retirees

Pension, Social Security and investment income can all count. Talk to us about how yours is documented.

Self-employed in Marco Island? No tax returns needed.

Many Marco Island owners still own the business that paid for the home, often in another state, and their tax returns rarely show the deposits. The Bank Statement HELOC qualifies you on 12 months of bank statements with an expense factor as low as 25% and a 660 minimum credit score, on lines up to $1,000,000. Strong credit and plenty of equity? The No-Doc HELOC skips income documentation altogether.

Keep your low first-mortgage rate

If you locked a first mortgage in the 3s or low 4s, protecting it matters. A HELOC sits alongside your existing loan instead of replacing it, so you tap equity without resetting your whole mortgage at today’s rates.

  • Your first mortgage and its rate stay untouched
  • Borrow only what you draw, when you draw it
  • Reuse the line as you pay it back down
  • Access up to 90% of your Marco Island home’s value
HELOC vs. cash-out refinance
Digital HELOC
Keeps your first mortgage. Adds a line only on the equity you want.
×
Cash-out refinance
Replaces your whole mortgage at today’s rate to pull cash out.
For Marco Island owners holding a low pandemic-era rate, a HELOC is usually the cheaper way to reach your equity.

What Marco Island homeowners use a HELOC for

Every situation is different, but the reasons Marco Island owners tap their equity tend to rhyme:

See the Marco Island HELOC rate you’ll actually get

No generic teaser numbers. Tell us about your Marco Island home and finances, and we’ll show you a rate built around your equity, not somebody else’s.

Home value & equity Loan-to-value (LTV) Credit score Draw amount Property type
See my live rate Takes a few minutes · won’t affect your credit score
What are HELOC rates in Marco Island right now? +
Our Marco Island Digital HELOC rates start at 6.75%*, personalized to your home value, loan-to-value, credit score, draw amount and property type. Checking your rate will not affect your credit score.
How much can I borrow against my Marco Island home? +
Lines run from $50,000 up to $1,000,000, and you can access up to 90% of value. On a $950,000 home with $300,000 owed, 90% of value is $855,000, leaving a line as large as about $555,000, subject to underwriting.
Can I get a HELOC on a Marco Island condo with an assessment pending? +
Often, yes. We review the building’s budget, reserves and assessment as part of the file, and a HELOC is one of the most common ways owners pay the assessment itself.
Can I get a HELOC on a Marco Island second home or rental? +
Yes. The Digital HELOC is available on second homes and investment properties in Florida, not just primary residences. Loan-to-value limits differ by occupancy.
I’m self-employed. Can I still qualify? +
Yes. Our Bank Statement HELOC lets qualified self-employed borrowers document income with 12 months of bank statements instead of tax returns, with a 660 minimum credit score. With a 700+ score and enough equity, the No-Doc HELOC needs no income documentation at all.
Do you lend in Marco Island? Your office is in Miami. +
Yes. On Mortgage holds a Florida mortgage broker license, which covers the entire state, and the Digital HELOC is fully online from application to closing. A Marco Island file is handled exactly like a Miami-Dade file, with no branch visit.
Will a HELOC affect the low rate on my first mortgage? +
No. A HELOC is a separate second lien. Your first mortgage, its balance and its rate stay exactly as they are.
Loan programs

Every way to tap your Marco Island home equity

Whether you are salaried, self-employed, investing or would rather not document income at all, there is a program built for your situation.

Nearby areas

HELOC guides for nearby cities

We lend across all of Florida. If you own property nearby, these local guides may help too.

Ready to tap your Marco Island home equity?

Marco Island HELOC rates starting at 6.75%*, personalized to you in minutes.